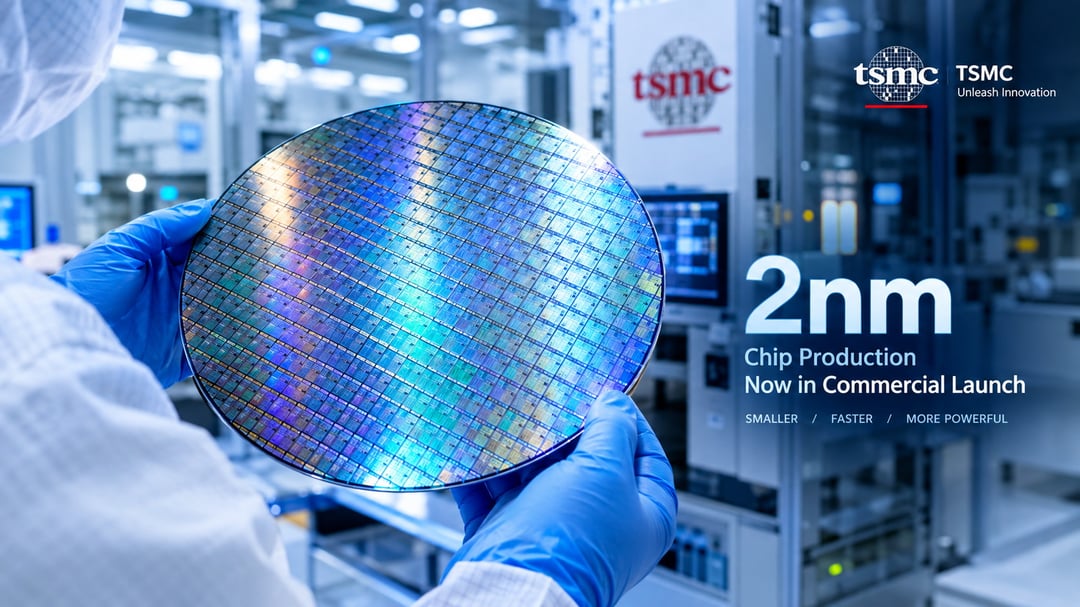
Taiwan Semiconductor Manufacturing Company has shifted its 2-nanometer chip process into commercial production. MediaTek stands as an early customer for the technology. Shares of the foundry climbed roughly 3% on Thursday, September 17, and closed at $430.26 on the New York Stock Exchange. Investors responded to the manufacturing step and the company’s record quarterly results.
MediaTek’s Dual-Node Approach for Smartphone Chips
MediaTek chose TSMC’s 2nm process for its Dimensity 9600 Pro smartphone processor. The company kept the broader-market Dimensity 9600M on the established 3nm node. According to the details provided, the Pro chip’s neural-processing unit improves prompt handling by 51% compared with the previous generation. Smartphones that use both processors are expected to reach the market soon.
This split strategy opens a commercial route for TSMC’s 2nm silicon beyond technical demonstrations. At the same time, it lets the foundry continue filling mature 3nm capacity with higher-volume products. Two-nanometer chips accounted for only 3% of TSMC’s second-quarter wafer revenue. By comparison, 3nm contributed 30% and 5nm contributed 33%. The figures show how early the transition still is.
Record Quarterly Results and Raised Guidance
TSMC reported second-quarter 2026 revenue of approximately $40.2 billion. Gross margins reached 67.7%. High-performance computing made up 66% of the total. Monthly numbers kept rising. August revenue hit a record NT$514.8 billion, or roughly $16.1 billion. That figure marked a 53.3% increase from the same period a year earlier.
Management lifted its full-year 2026 growth guidance to slightly above 40%. The update improves on earlier expectations and points to continued strong demand for advanced manufacturing capacity. The company also announced plans to expand operations in Longtan, Taiwan, for processes at 1.4nm and below.
Pressures on the Production Ramp
The move into volume production brings its own challenges. TSMC’s larger capital expenditure budget increases exposure to long-dated fab projects. That spending could stretch free cash flow in the near term. Analysts plan to watch how quickly the 2nm lines fill and whether yields hold as production scales. The company is scheduled to report its next quarterly results on October 14.
TSMC holds a Strong Buy consensus rating. The average analyst price target sits at $547.38, according to TipRanks. Some valuation frameworks, however, indicate the shares trade above intrinsic value at current levels.